How Life Insurance Fits Into Your Financial Plan
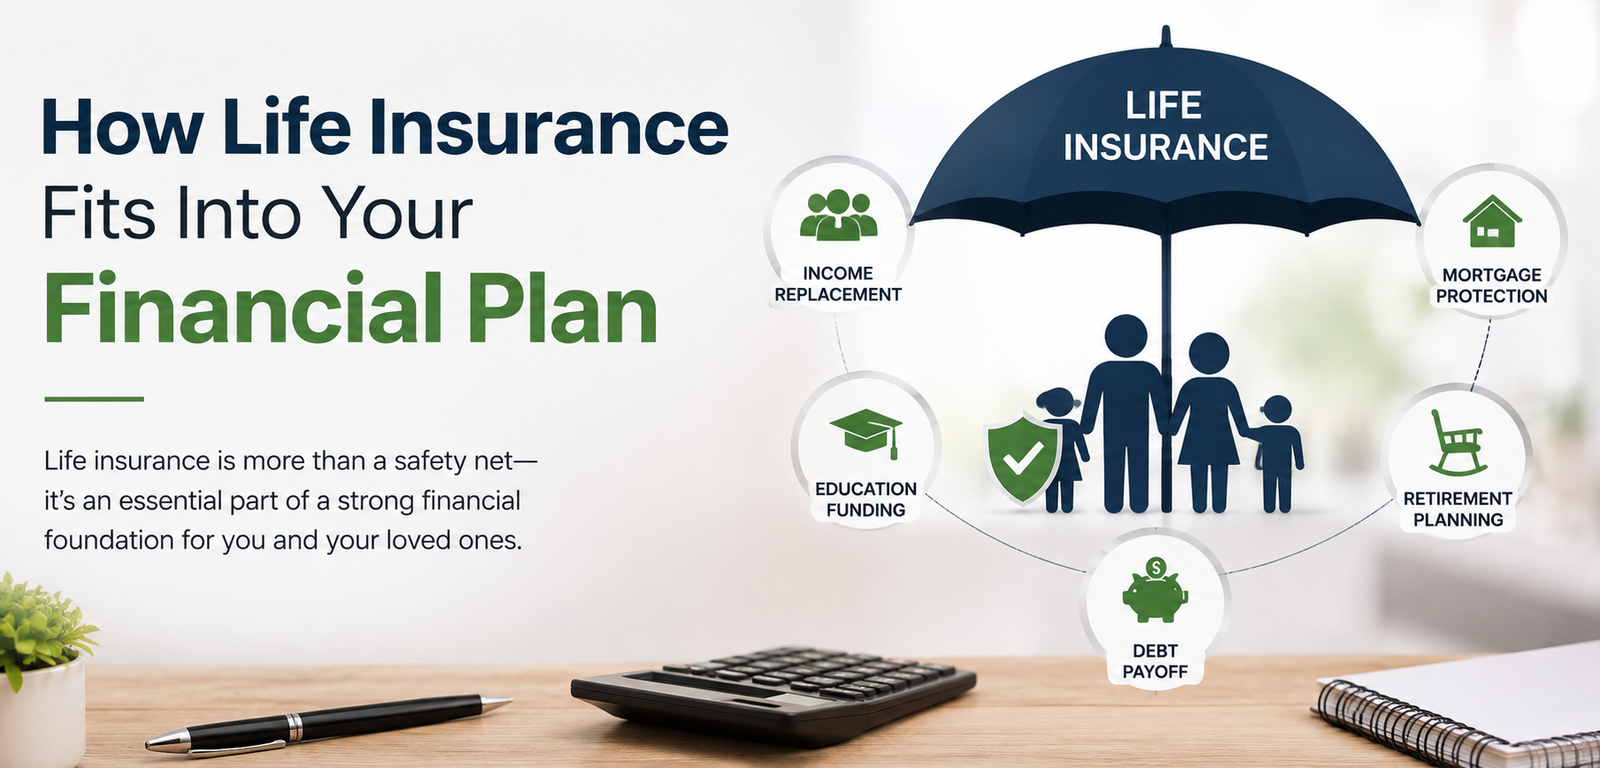
Life insurance is often viewed simply as a way to provide money to your family after you die. While protecting loved ones is one of its most important purposes, life insurance can also play a broader role in a well-rounded financial plan. When properly selected and regularly reviewed, a life insurance policy can help protect income, support long-term financial goals, cover outstanding debts, provide funds for education, and create greater financial stability for your family.
Understanding where life insurance fits into your overall financial strategy can help you make more informed decisions about the amount and type of coverage you may need.
What Role Does Life Insurance Play in Financial Planning?
A financial plan typically includes several important areas, such as income, savings, investments, retirement, debt management, emergency funds, and protection against unexpected events.
Life insurance belongs primarily in the protection part of your financial plan.
If your income helps support your household, your unexpected death could create a significant financial gap. Your family may still have to pay for housing, utilities, food, education, debts, and other expenses. Life insurance can provide a death benefit to your beneficiaries, helping them manage those financial responsibilities.
For many families, the goal is not simply to leave money behind. The goal is to make sure the people who depend on you have the financial resources they need to continue their lives with fewer financial disruptions.
Replacing Lost Income
One of the biggest financial risks for a family is the loss of a primary income earner.
Suppose you earn $60,000 per year and your spouse or children depend significantly on your income. If you were no longer there to provide that income, your family could face years of financial challenges.
Life insurance can help replace some of that lost income.
The appropriate coverage amount depends on factors such as your income, age, number of dependents, existing savings, debts, and long-term financial goals. Some people use a multiple of their annual income as a starting point, while others calculate their specific financial obligations and future needs.
A financial needs analysis can provide a more personalized estimate.
Protecting Your Family’s Financial Goals
Most families have financial goals beyond paying monthly bills. These might include buying a home, paying for children’s education, building retirement savings, or helping loved ones financially.
Without adequate life insurance, the death of a parent or spouse could force the family to change those plans.
For example, if you have young children and both parents are working toward funding future education, the loss of one parent’s income could make that goal much harder to achieve.
Life insurance can provide a financial resource that helps your family continue pursuing important goals even after an unexpected loss.
Life Insurance and Mortgage Protection
For many homeowners, a mortgage is one of the largest financial obligations they have.
If you die while a mortgage is still outstanding, your family may have to continue making payments without your income. Depending on the policy and the family’s financial situation, the death benefit from life insurance could be used to help pay the remaining mortgage balance.
This does not necessarily mean that every homeowner should purchase enough life insurance to completely pay off the mortgage. Your overall financial plan should consider your savings, other assets, income, existing coverage, and your family’s needs.
The important point is that your mortgage should be included when determining how much life insurance coverage may be appropriate.
Supporting Children’s Education
Parents often spend years planning for their children’s education.
College and other educational expenses can represent a substantial future financial commitment. If a parent dies unexpectedly, the surviving family may need to redirect money that was intended for education toward immediate living expenses.
Life insurance can provide additional financial resources that may help preserve an education fund.
When determining your coverage needs, consider both current expenses and major future obligations. Education costs are only one part of the calculation, but they can be important for families with children.
Life Insurance and Retirement Planning
Life insurance and retirement planning serve different purposes, but they can work together as components of an overall financial strategy.
Retirement savings are generally designed to provide income and financial resources during your later years. Life insurance, on the other hand, is primarily designed to provide financial protection against premature death.
For example, if one spouse dies before retirement, the surviving spouse may lose part of the household’s expected retirement income. Life insurance can potentially provide funds that help reduce the financial impact.
Certain permanent life insurance policies may also accumulate cash value. However, these policies can be more complex than term insurance and may involve higher premiums, fees, and other considerations.
Life insurance should not automatically replace retirement accounts or other investments. Instead, each financial tool should be evaluated based on its purpose, costs, risks, and suitability for your circumstances.
Term vs. Permanent Life Insurance in a Financial Plan
One of the most important decisions is choosing between term and permanent life insurance.
Term Life Insurance
Term life insurance provides coverage for a specific period, such as 10, 20, or 30 years.
It is often considered when the primary goal is income protection during working years or while children are financially dependent.
For example, a parent with young children and a mortgage may want coverage during the years when the family’s financial obligations are highest.
Term insurance generally does not build cash value.
Permanent Life Insurance
Permanent life insurance is designed to provide coverage that can last for the insured person’s lifetime, provided the policy remains in force.
Some types of permanent policies include a cash-value component. Examples include whole life and universal life insurance.
Because permanent policies can have additional features and costs, they require careful consideration. The right choice depends on your financial goals, budget, need for long-term coverage, and understanding of the policy’s terms.
Using Life Insurance to Manage Debt
Debt is another important part of financial planning.
Common obligations may include:
- Mortgages
- Personal loans
- Auto loans
- Credit card balances
- Business-related debt
- Other financial obligations
If you die with significant debt, your family may face financial pressure depending on the type of debt and how it is structured.
Life insurance can provide beneficiaries with funds that may be used to address eligible financial obligations. This can help prevent surviving family members from having to make major financial decisions during an already difficult period.
When calculating your coverage needs, make a list of your major debts and determine which ones should be considered in your overall protection strategy.
Protecting a Stay-at-Home Parent
Life insurance is not only important for the person earning the largest paycheck.
A stay-at-home parent may provide childcare, household management, transportation, meal preparation, and many other services that would be expensive to replace.
If that parent dies, the surviving parent may need to pay for childcare or reduce working hours to manage household responsibilities.
Life insurance can help provide financial resources for these costs.
This is why both spouses or partners should consider their economic contribution when evaluating life insurance needs.
Business Owners and Life Insurance
Life insurance can also play an important role in business planning.
Business owners may have employees, partners, loans, investors, and family members who depend on the success of the company.
In some circumstances, life insurance can be used as part of a business continuity strategy or to address obligations associated with business ownership.
Business-related life insurance arrangements can be complicated, particularly when multiple owners are involved. Business owners should understand policy ownership, beneficiaries, tax considerations, and applicable legal agreements before implementing a strategy.
Professional advice may be appropriate for complex situations.
How Much Life Insurance Do You Need?
There is no single coverage amount that works for everyone.
A useful starting point is to consider:
Financial obligations + future goals + income replacement needs − existing financial resources = potential coverage need
You might evaluate:
- Current annual income
- Number and age of dependents
- Mortgage balance
- Other debts
- Children’s future education costs
- Existing savings
- Existing life insurance
- Retirement assets
- Funeral and final expenses
- Future financial goals
Your circumstances can change over time, so the amount that makes sense today may not be appropriate several years from now.
Don’t Forget Beneficiaries
Choosing the right beneficiary is an essential part of life insurance planning.
A beneficiary is the person or entity designated to receive the policy’s death benefit according to the policy terms.
Life events can change your beneficiary needs. Marriage, divorce, the birth of a child, death of a beneficiary, or changes in family relationships may all be reasons to review your beneficiary designations.
It is important to keep beneficiary information current and understand how your policy handles primary and contingent beneficiaries.
Reviewing Life Insurance as Your Life Changes
A financial plan should not remain unchanged forever.
Your income may increase. Your mortgage may decrease. Your children may become financially independent. You may start a business, get married, divorce, retire, or experience other major life changes.
Each of these events can affect your insurance needs.
Reviewing your coverage periodically can help you determine whether your policy still matches your financial situation.
A review should consider:
- Coverage amount
- Policy type
- Policy duration
- Premiums
- Beneficiaries
- Outstanding debts
- Income
- Dependents
- Financial goals
Life Insurance Is One Piece of the Bigger Financial Picture
Life insurance is important, but it is only one part of a complete financial strategy.
A strong financial plan may also include an emergency fund, retirement savings, investments, disability protection, health coverage, debt management, estate planning, and other financial tools.
The purpose of life insurance is to address a specific risk: the financial consequences of death.
By identifying that risk and choosing appropriate coverage, you can create a stronger financial foundation for the people who depend on you.
Final Thoughts
Life insurance can fit into your financial plan in several ways. It can help replace lost income, protect your family from financial hardship, support education goals, address mortgage and debt obligations, and provide additional financial security during difficult circumstances.
The right policy depends on your individual financial situation. There is no universal amount of coverage or single policy type that is right for everyone.
The most important step is to understand what your family would financially need if your income were suddenly gone. From there, you can evaluate your existing resources and determine whether life insurance can help fill the gap.
As your life and financial situation change, your insurance needs may change as well. Regular reviews can help ensure that your coverage continues to support the people and goals that matter most.
Life insurance is not just about preparing for the unexpected. It is about building a financial plan that helps protect the future you are working to create.
Frequently Asked Questions
Is life insurance part of financial planning?
Yes. Life insurance can be an important part of a financial plan because it can help protect dependents from the financial consequences of an unexpected death.
How much life insurance should I have?
The appropriate amount depends on your income, debts, dependents, existing assets, future goals, and other financial obligations.
Should both spouses have life insurance?
Both spouses may benefit from coverage, particularly when each person contributes income or valuable household services.
Can life insurance help with a mortgage?
A life insurance death benefit may provide beneficiaries with funds that can be used toward mortgage payments or other financial obligations, depending on their needs and circumstances.
Should I review my life insurance policy regularly?
Yes. Major changes in income, family circumstances, debt, employment, or financial goals can affect the amount and type of coverage that may be appropriate.