Life Insurance for Mortgage Protection
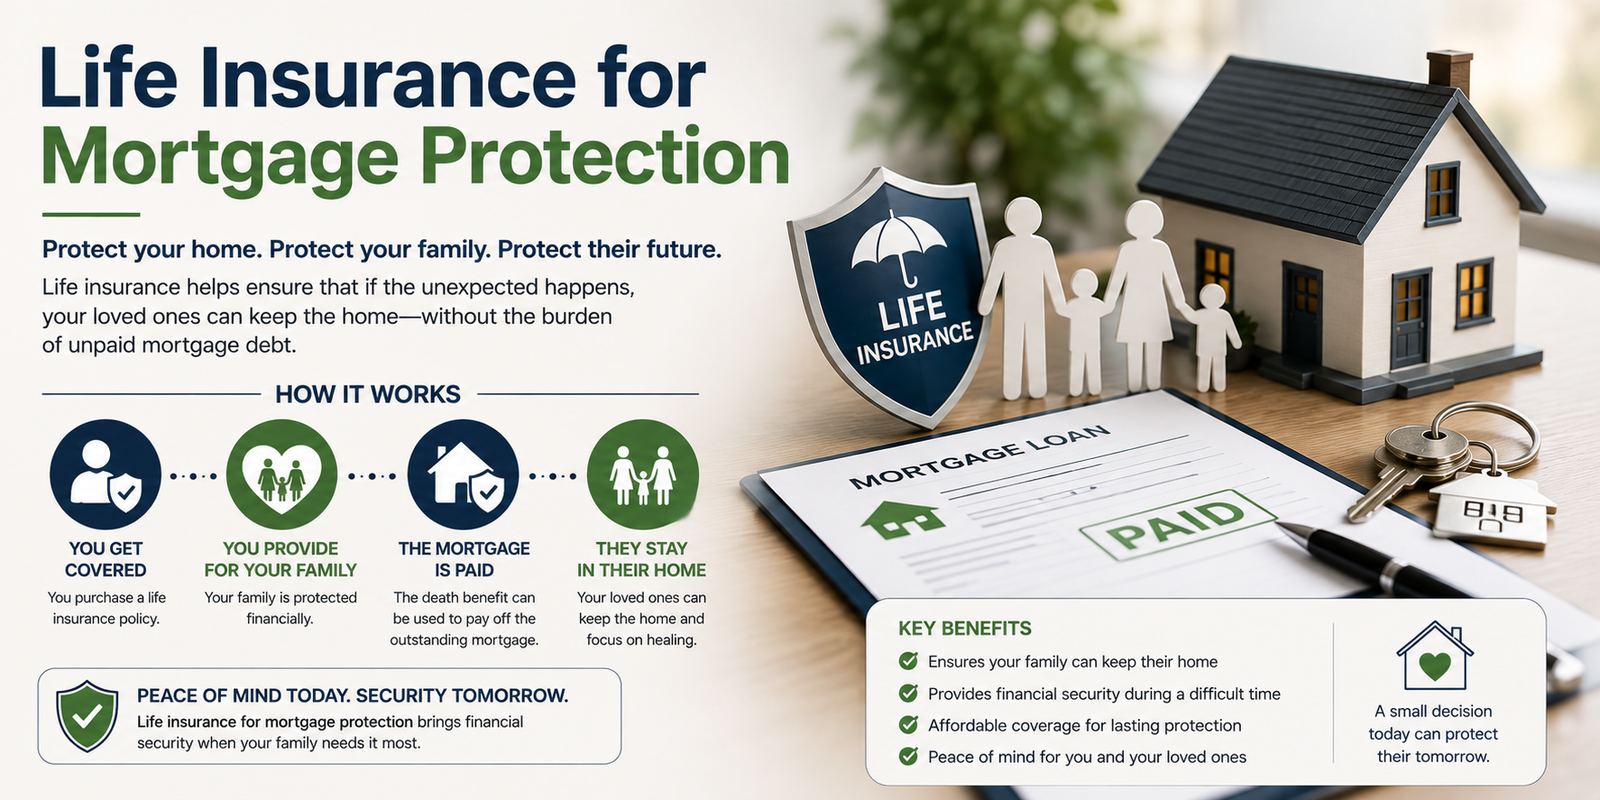
Buying a home is one of the biggest financial commitments many people make. For most homeowners, a mortgage can last for decades and represent a significant portion of the household’s monthly budget. While owning a home can provide stability and security, it also creates a financial responsibility that should be considered when building a life insurance plan.
Life insurance for mortgage protection can help provide financial resources to your loved ones if you die while your mortgage is still outstanding. Depending on the policy and your family’s circumstances, the death benefit may help pay mortgage payments, reduce the remaining loan balance, or cover other household expenses.
The goal is simple: help protect your family and their ability to remain financially secure in the home you worked hard to build.
What Is Life Insurance for Mortgage Protection?
Life insurance for mortgage protection generally refers to using life insurance coverage to help protect a family from the financial burden of an outstanding mortgage after the death of the insured person.
It is important to understand that mortgage protection does not necessarily mean purchasing a special type of life insurance policy. In many situations, a standard term or permanent life insurance policy can provide a death benefit that beneficiaries may use toward mortgage-related expenses.
For example, imagine you have a 25-year mortgage and still owe $250,000. If you die unexpectedly, your family may still be responsible for the mortgage. If your income was an important part of the household budget, continuing those payments could become difficult.
Life insurance can provide a financial resource that may help your family manage that obligation.
Why Mortgage Protection Matters
A mortgage is usually a long-term financial commitment.
Even if your family has savings, an unexpected death could create several financial challenges at the same time. Your loved ones may have to deal with funeral expenses, household bills, childcare, education costs, and lost income while also managing the mortgage.
Without adequate financial protection, the surviving family member may face difficult choices.
They might need to:
- Use savings to make mortgage payments
- Sell investments
- Reduce other household expenses
- Move to a less expensive home
- Take on additional debt
- Sell the property
Appropriate life insurance coverage may help reduce the pressure created by these decisions.
How Does Mortgage Protection Through Life Insurance Work?
The basic concept is straightforward.
You purchase a life insurance policy and select an appropriate coverage amount. You pay the required premiums to keep the policy active. If you die while the policy is in force, the insurer generally pays the death benefit according to the policy terms.
Your beneficiaries can then use the funds for their financial needs.
For example, if your life insurance policy provides a $500,000 death benefit and your mortgage balance is $250,000, your beneficiaries may potentially use part of the benefit toward the mortgage while using the remaining funds for other needs.
The exact use of the death benefit depends on the policy structure, beneficiary arrangements, applicable laws, and the family’s financial circumstances.
Term Life Insurance for Mortgage Protection
Term life insurance is often considered for mortgage protection because it provides coverage for a specific period.
Suppose you have a 30-year mortgage. You might consider a 20- or 30-year term policy depending on your financial goals and circumstances.
One advantage of term insurance is that it can provide substantial coverage for a specified period, often at a lower initial premium than comparable permanent insurance.
The idea is to have protection during the years when your mortgage balance and financial responsibilities may be significant.
However, the appropriate term length should be based on your broader financial plan rather than simply matching the mortgage term.
Permanent Life Insurance for Mortgage Protection
Permanent life insurance is designed to provide coverage that can continue for the insured person’s lifetime, subject to the policy’s terms and requirements.
Whole life and universal life insurance are examples of permanent policies.
Some permanent policies may also accumulate cash value. This can make them different from term insurance, which generally does not build cash value.
Permanent coverage can be useful in certain long-term financial strategies, but it typically costs more than term insurance. Because of the additional features and costs, homeowners should carefully evaluate whether permanent insurance fits their financial objectives.
Mortgage protection is only one potential reason to purchase permanent life insurance.
How Much Life Insurance Should You Have for Your Mortgage?
One common mistake is assuming that the mortgage balance alone determines the amount of life insurance needed.
Your mortgage is important, but your family’s total financial needs may be much greater.
For example, suppose your family owes $200,000 on the mortgage. You might initially think $200,000 of life insurance is enough.
But what about:
- Lost income?
- Childcare?
- Education?
- Credit card debt?
- Auto loans?
- Emergency expenses?
- Funeral costs?
- Future financial goals?
If you purchase only enough coverage to pay off the mortgage, your family may still face significant financial challenges after your death.
A better approach is to consider the mortgage as one component of your total life insurance needs.
Should Life Insurance Pay Off the Entire Mortgage?
Not necessarily.
Some families may prefer to use the death benefit to completely pay off the mortgage. This can eliminate a major monthly expense and provide greater housing security.
Others may decide that keeping the mortgage and using part of the death benefit for income replacement, education, or investments makes more financial sense.
There is no universal answer.
The right approach depends on factors such as interest rates, household income, other assets, investment goals, mortgage terms, and the needs of your beneficiaries.
The most important thing is to make sure your coverage is sufficient to address your family’s overall financial situation.
Life Insurance vs. Mortgage Protection Insurance
Homeowners sometimes confuse traditional life insurance with mortgage protection insurance.
Traditional life insurance generally provides a death benefit to the policy’s beneficiaries. Those beneficiaries can typically use the funds for a variety of financial purposes, subject to the policy terms and applicable rules.
Mortgage protection products may be designed specifically around mortgage debt and can have different structures.
When comparing these options, consider:
- Coverage amount
- Premium cost
- Policy duration
- Beneficiary structure
- Death benefit
- Flexibility
- Policy exclusions and conditions
- What happens if you refinance or sell your home
Understanding these differences can help you determine which type of protection better fits your financial plan.
Protecting Your Family’s Ability to Stay in Their Home
For many families, a home is more than a financial asset.
It is where children grow up, where family memories are created, and where people expect to build their future.
The loss of a parent or spouse can already be emotionally difficult. Adding the possibility of losing the family home can create additional stress.
Life insurance can provide financial flexibility that may allow the surviving family members to remain in their home if they choose to do so.
This can be especially important when the surviving spouse has children or other dependents.
Don’t Forget About Income Replacement
Mortgage protection should not be viewed separately from income replacement.
Imagine that your mortgage payment is $2,000 per month. Paying off the mortgage could eliminate that payment, but your family could still lose a significant portion of household income.
They may still need money for:
- Food
- Utilities
- Transportation
- Healthcare
- Childcare
- Education
- Property taxes
- Home maintenance
- Retirement savings
For this reason, a broader life insurance needs analysis is usually more useful than focusing exclusively on the mortgage balance.
What Happens If You Refinance Your Mortgage?
Mortgage terms can change.
You may refinance your home, move to a new property, pay down your loan faster, or take on additional debt.
This is another reason to review your life insurance coverage periodically.
If you originally purchased a policy based on a specific mortgage balance, your financial needs may look very different several years later.
Life insurance should be reviewed as part of your overall financial planning process rather than treated as a set-it-and-forget-it product.
Life Insurance for Joint Homeowners
Couples who own a home together should consider what would happen financially if either person died.
If both people contribute income toward the mortgage, the death of one spouse could significantly change the household’s financial situation.
Even when only one spouse earns income, the other spouse may contribute valuable unpaid services such as childcare and household management.
Both partners should consider their economic contributions when evaluating life insurance needs.
What Should You Consider Before Buying Coverage?
Before purchasing life insurance for mortgage protection, consider your complete financial situation.
Start by reviewing:
1. Mortgage Balance
Find out how much you currently owe and how quickly the balance is expected to decline.
2. Monthly Mortgage Payment
Consider whether your family could comfortably afford the payment if one income disappeared.
3. Household Income
Determine how much income would be lost if you died.
4. Other Debts
Include credit cards, personal loans, auto loans, student loans, and other significant obligations.
5. Savings and Investments
Existing financial assets may reduce the amount of life insurance your family needs.
6. Number of Dependents
Children and other dependents can increase the amount of financial protection required.
7. Future Goals
Consider education, retirement, home improvements, and other long-term financial goals.
Common Mistakes to Avoid
Buying Only Enough Coverage to Pay the Mortgage
The mortgage is only one financial obligation. Your family may need additional money for income replacement and other expenses.
Choosing a Policy Based Only on Price
The cheapest policy is not necessarily the most suitable. Consider coverage amount, term, insurer strength, policy features, and your long-term needs.
Forgetting to Update Beneficiaries
Life changes can affect who should receive the death benefit. Review beneficiary information after major life events.
Ignoring Inflation
The purchasing power of money can change over time. Consider future expenses rather than focusing only on today’s costs.
Failing to Review Coverage
Your mortgage, income, family, and financial goals can change. Your insurance should be reviewed accordingly.
How to Determine the Right Strategy
A practical approach is to start with your family’s financial needs.
Add major obligations such as:
Mortgage + other debts + future expenses + income replacement needs
Then consider assets that may already be available:
Savings + investments + existing life insurance
The difference can provide a starting point for determining potential life insurance needs.
This is only a general framework. Your actual needs can vary significantly depending on your financial circumstances.
Final Thoughts
Life insurance for mortgage protection can be an important part of a family’s financial strategy.
A mortgage may be one of the largest debts a household carries, and the loss of an income earner can make continuing those payments more difficult. Life insurance can provide beneficiaries with financial resources that may help them manage the mortgage while also addressing other important expenses.
However, mortgage protection should not be the only factor considered when choosing coverage.
A strong life insurance strategy should take into account income replacement, debts, children, education, savings, retirement goals, and other financial responsibilities.
For some homeowners, term life insurance may provide affordable protection during important working years. Others may have long-term reasons to consider permanent life insurance.
The best choice depends on your individual circumstances and financial goals.
Ultimately, the purpose of mortgage protection is not simply to protect a loan. It is about protecting the people who depend on you and giving them financial options during one of life’s most difficult moments.
Frequently Asked Questions
Can life insurance be used to pay off a mortgage?
Yes. Beneficiaries may generally use life insurance proceeds toward mortgage payments or other financial needs, depending on the policy and applicable circumstances.
How much life insurance should I have if I have a mortgage?
Your mortgage balance is an important consideration, but you should also consider income replacement, other debts, dependents, future expenses, savings, and existing insurance.
Is term life insurance good for mortgage protection?
Term life insurance can be suitable for homeowners who want coverage during a specific period, such as their working years or the years when their mortgage and family obligations are substantial.
Should both spouses have life insurance?
Both spouses may benefit from coverage if each contributes income or valuable household services.
Does mortgage protection replace regular life insurance?
Not necessarily. A broader life insurance policy may provide beneficiaries with greater flexibility because the death benefit can potentially be used for the mortgage and other financial needs.
Should I review my mortgage-related life insurance coverage?
Yes. Changes to your mortgage, income, family, debts, savings, or financial goals may affect how much coverage you need.